
DIVORCE REAL ESTATE + RCS-D™ SERVICES
When the Home
Is Part of the Decision.
DIVORCE REAL ESTATE + RCS-D™ SERVICES When the House Is Part of the Decision. Keep the House for All the Right Reasons™ By preventing permanent mistakes before mediation.
In divorce, decisions about the house are permanent. Jenny Turley, RCS-D™ designee, helps divorcing homeowners and their professional teams get the facts about the house before mediation: the evidence, the documents, the market, and the mortgage realities.
Serving Chattanooga, Hamilton County, and surrounding Southeast Tennessee communities.
Jenny Turley | RCS-D™ Real Estate Collaboration Specialist – Divorce™ Designee
WHEN DIVORCE + REAL ESTATE INTERSECT
The House
Is More Than
a Listing.
The house is often the largest asset in a divorce, and one of the most document-intensive. When those documents are missing at mediation, a guessed value or an unknown lien can become one spouse's permanent problem.
PROPERTY
What is the house's condition, and which repairs will someone have to pay for after the divorce?
MARKET
What do Chattanooga-area comparable sales indicate? Is an online estimate being treated as the value?
EQUITY + OBLIGATIONS
Which loans, liens, and property-related debts should be verified with the appropriate financial and legal professionals before anyone relies on an equity number?
NEXT STEP
Keep, sell, refinance, buy out, or prepare for a future sale. Every path carries different risks. Keeping the house carries the most.
Don't Settle for a Risky Property Settlement. Because property division is permanent, a mistake about the house can lead to damaged credit, foreclosure, bankruptcy, or post-divorce legal fees.
TWO SIDES OF THE WORK
Support for Homeowners.
A Resource for Professionals.
FOR ATTORNEYS, MEDIATORS + FINANCIAL PROFESSIONALS
Before mediation, Jenny and her house due diligence TEAM gather house documents and information to help resolve real estate gaps in the case file and the marital balance sheet.
Family lawyers and mediators: house documents and evidence to support informed decision making about the house and secured house debt.
CDFAs and financial professionals: house-related figures backed by documents, for the marital balance sheet.
Mortgage professionals: an agent who works alongside you when refinance-ability is in question, and plans the sale when it isn't there.
Jenny's role stays divorce real estate. Legal, tax, financial, and mortgage determinations remain with each professional.
FOR HOMEOWNERS
You do not need to understand the whole divorce real estate process, or know what should happen to the house, before reaching out.
Jenny helps you gather the house documents you'll need, understand the local market, and bring the right questions to your lawyer and a licensed mortgage professional, so the decision you make at mediation is an informed one. If the house is sold, Jenny handles pricing, preparation, listing strategy, and the transaction, and helps each of you plan the next move.
The goal: protect each spouse's credit and preserve each spouse's ability to own a house again.
SPECIALIZED DIVORCE REAL ESTATE TRAINING
What is an
RCS-D™?
RCS-D™ stands for Real Estate Collaboration Specialist – Divorce™, a professional designation for real estate and mortgage professionals from DivorceThisHouse.com
In divorce court, emotions count against each spouse. Under the RCS-D™ framework we approach divorce real estate as a business transaction in the best interest of the house, ™ and each divorcing spouse.™
The RCS-D™ designation training was developed and is taught by Prof. Kelly Lise Murray, JD, who holds degrees from Stanford University and Harvard Law School and served eighteen years on the faculty of Vanderbilt Law School before retiring in 2023. Because divorce is governed by state law, RCS-D™ training is state-specific, drawing on what actually goes wrong in litigated divorce cases involving real estate and debt.
The role is real estate.
The approach is collaboration.
Jenny can work alongside the attorneys, financial professionals, mortgage professionals, and other specialists involved while remaining focused on the real estate component of the situation.
Divorce real estate guidance does not replace legal, tax, financial, mortgage, or appraisal advice.
CONNECT WITH JENNY
423-653-0881
Commitment · Consumer Protection · Credibility · Collaboration · Compassion
DIVORCE MORTAGE MATH THAT MATTERS BEFORE MEDIATION
Keeping the House
is the Riskiest Choice.
It can still be the right one, for the right reasons.
Selling ends the joint mortgage. Keeping the house is the only path where the loan, the house, and one household's income all have to keep working after the divorce is final. Before mediation, two questions need real answers:
01
Refinance-ability
Can the spouse keeping the house get the other spouse off the joint mortgage? Funded. Not applied for. Not promised.
02
Fund-ability
Can the buyout be funded, can the house be carried, and can each spouse fund their next house?
FOR HOMEOWNERS
The Math First.
Jenny helps you take these questions to a licensed mortgage professional.
100%. Not half
On a joint mortgage, each borrower owes the entire balance. Until the other spouse is off the loan or the house sells, a divorce decree doesn't change that.
Two ways off, not three
A funded refinance (or underwritten assumption) or a sale. An application is not a refinance. A promise to refinance is not a refinance.
One family income, two households
A refinance can close and still leave you house poor. Taxes, insurance, repairs, and maintenance now fall on one household.
One late payment, two credit scores. A late payment on a joint mortgage lands on both spouses' credit. Damaged credit may take 12 months or longer to recover. (Source: FICO Blog)
What Else Divorcing Homeowners Are Often Surprised to Learn
➜ No divorce court can order a lender to approve a loan.
➜ Support counts as refinance income only with a paper trail of payments. That takes months, and the refinance deadline in an agreement can be shorter.
➜ Keeping the existing loan (assumption) has its own hurdles. Conventional loans are generally not assumable; FHA, VA, and USDA loans can be. Even then:
Equity gap: the spouse keeping the house must pay cash or secure a second loan to cover the difference between the buyout and the remaining loan balance.
Qualification: the spouse keeping the house must still pass credit, income, and debt-to-income underwriting.
Processing time: approvals through the current loan servicer typically take months.
THE SQUEAK-BY REFI
Beware the "Squeak-By Refi."™
A refinance that barely qualifies has no margin for a higher insurance premium, a tax increase, a new roof, or a change in support. And the house may be sold anyway - later, under pressure, and on worse terms.
FOR ATTORNEYS, MEDIATORS + FINANCIAL PROFESSIONALS
Before the Agreement Says “Refinance”
Before mediation, Jenny works with licensed mortgage professionals so the case file answers these questions with documents.
➜ Can the spouse keeping the house refinance or assume the loan, and will it fund by the deadline in the agreement?
➜ What income will a lender count, and when will it count?
➜ Can the buyout be funded?
➜ If the refinance or assumption doesn't fund, what happens to the house?
"A divorce agreement without deadlines and consequences is not a plan. It's a hope."
- Prof. Kelly Lise Murray, JD
Each Spouse Can Know
Before Mediation.
Under the federal Equal Credit Opportunity Act, marital status is a protected class. Each spouse can meet with a licensed mortgage professional before mediation. You do not have to pay for a written pre-approval or other federal mortgage guidelines information provided by a licensed mortgage professional.
When the house is unrefinance-able, deciding at mediation to sell it may improve legal and financial outcomes for property division.
Keep the House for All the Right Reasons™
Know what you OWE, know what you OWN, and know what you're getting stuck with.
Jenny does not give mortgage or legal advice. Mortgage questions are answered by a licensed mortgage professional; legal questions by counsel.
WHY JENNY SPECIALIZES
Why Jenny Specializes
in Divorce Real Estate.
To help protect each spouse's credit score.
To help preserve each spouse's eligibility to own a house again.
And if the house is sold, she hopes to be considered for the listing.
"Tangible things such as documents often have 'enhanced reliability' especially when the judge can refer to them during decision making."
- Hon. Rodney Equi, Master the Rules of Evidence: They Are Key to Conveying Your Case, Fam. Advoc., Fall 2008, at 26, 28
A PROPERTY FOCUSED PROCESS
Start With
What We Know.
Every situation is different. The process begins by bringing structure to the divorce real estate questions.
01
UNDERSTAND THE SITUATION
Identify the property, the people involved, and where the divorce stands. Start early. Before mediation, more options remain.
02
UNDERSTAND THE PROPERTY
Review the house's condition, location, and property information, and help gather the house evidence, documents, and information that are often missing from a divorce file.
03
UNDERSTAND THE MARKET
Evaluate local market conditions, comparable sales, and buyer activity. An online estimate is not evidence of value, and a market analysis is not an appraisal.
04
IDENTIFY THE OPTIONS
Keep, sell, refinance, assume, or buy out. Before any path is chosen, the Refinance-ability and Fund-ability questions go to a licensed mortgage professional for each spouse.
05
BUILD THE DIVORCE REAL ESTATE PLAN
If a sale moves forward, establish the preparation, pricing, marketing, communication, and transaction strategy.
↓
"That includes a Get Ready First Budget™ for preparing the house before it goes to market."
06
MANAGE THE TRANSACTION
Manage the listing, offers, negotiations, inspections, deadlines, and closing, with communication both spouses and their professionals can follow.
CLEAR ROLES. BETTER COMMUNICATION
Real Estate Guidance
Is Not Legal Advice.
Divorce can involve legal, financial, tax, mortgage, appraisal, and real estate questions.
Jenny's role is focused on the property, the local real estate market, and the divorce real estate transaction. Attorneys, financial professionals, lenders, appraisers, and other specialists provide guidance within their respective areas of expertise.
When appropriate, Jenny can collaborate with those professionals so the real estate component of the situation is clearly understood.
Jenny gathers house evidence, documents, and information. She does not interpret agreements, give legal, tax, or mortgage advice, or tell anyone whether to keep the house. That decision belongs to you, made with the help of your professionals.
LOCAL DIVORCE REAL ESTATE GUIDANCE
Divorce Real Estate in Chattanooga + Southeast Tennessee.
Jenny Turley provides divorce-compliant real estate services in Chattanooga, Hamilton County, and surrounding Southeast Tennessee communities.
Local conditions matter. Neighborhood, property condition, inventory, comparable sales, buyer demand, and timing can all influence how a house should be positioned if it is ultimately placed on the market.
Tulip Partners also serves Northwest Georgia, and the team's broader real estate network can help when a move extends beyond Jenny's primary market.
DIVORCE REAL ESTATE FAQ
-
RCS-D™ stands for Real Estate Collaboration Specialist – Divorce™, a professional designation for real estate and mortgage professionals, developed and taught by Prof. Kelly Lise Murray, JD, through DivorceThisHouse.com.
-
A divorce-credentialed real estate professional addresses the real estate component of property due diligence. That may include evaluating the property and local market, preparing a house for sale, developing a listing strategy, managing a transaction, and coordinating property-related communication with clients and other professionals. Before mediation, an RCS-D™ also helps gather the house evidence, documents, and information that lawyers, mediators, and financial professionals need to complete the case file.
-
Not necessarily. But there are only two ways to remove a spouse from a joint mortgage: a funded refinance (or underwritten assumption) or a sale. Whether keeping the house works depends on Refinance-ability and Fund-ability, which you decide with your legal, financial, and mortgage professionals. Jenny provides the property and market information that decision needs.
-
Yes. When appropriate and authorized, Jenny can collaborate with attorneys and other professionals regarding the real estate component of the situation while remaining within her role as a divorce real estate professional. Ideally, that starts before mediation.
-
Yes. Jenny can evaluate the property, comparable sales, current inventory, buyer activity, and local market conditions to develop a real estate market analysis. A real estate market analysis is not the same as a formal appraisal. An online price estimate is not evidence of value. In divorce, an inaccurate number can become the value both spouses rely on.
-
Representation depends on the circumstances, applicable agency rules, brokerage requirements, and agreements between the parties. Jenny can explain the available real estate representation structure for the specific transaction.
-
Keeping the house is the riskiest choice. It can still be the right one. Before agreeing, the spouse keeping it should know whether they can get the other spouse off the mortgage and carry the house on one household's budget without a "squeak-by refi." Jenny provides the property and market information; mortgage, legal, tax, and financial professionals address qualification and the agreement.
-
Yes. Whether one spouse or both are buying, Tulip Partners can help each of you find a right-sized next house, and connect you with a trusted agent if your move takes you outside the area.
-
Yes. Jenny Turley of Tulip Partners provides RCS-D™ divorce real estate services in Chattanooga, Hamilton County, and surrounding Southeast Tennessee communities.
-
Before mediation. That is where decisions about the house get made, and property division is permanent. The next best time is now.
-
Sometimes, but it is not automatic. Conventional loans are generally not assumable; FHA, VA, and USDA loans can be. An assumption still requires credit, income, and debt-to-income underwriting, cash or a second loan to cover the equity gap, and approval through the current loan servicer typically takes months. Until the other spouse is off the loan, both borrowers owe 100%.
-
No court can make a lender approve a loan. Ask your lawyer how your agreement handles a refinance that doesn't fund, and ask a licensed mortgage professional whether it can fund by the deadline.
WHEN THE PROPERTY NEEDS A PLAN
Start With a
Private Conversation.
You do not need to have every decision made before reaching out.
If a house is part of a divorce, start with where things currently stand. Jenny can help identify the real estate questions that need to be answered and determine the appropriate next step for the property.
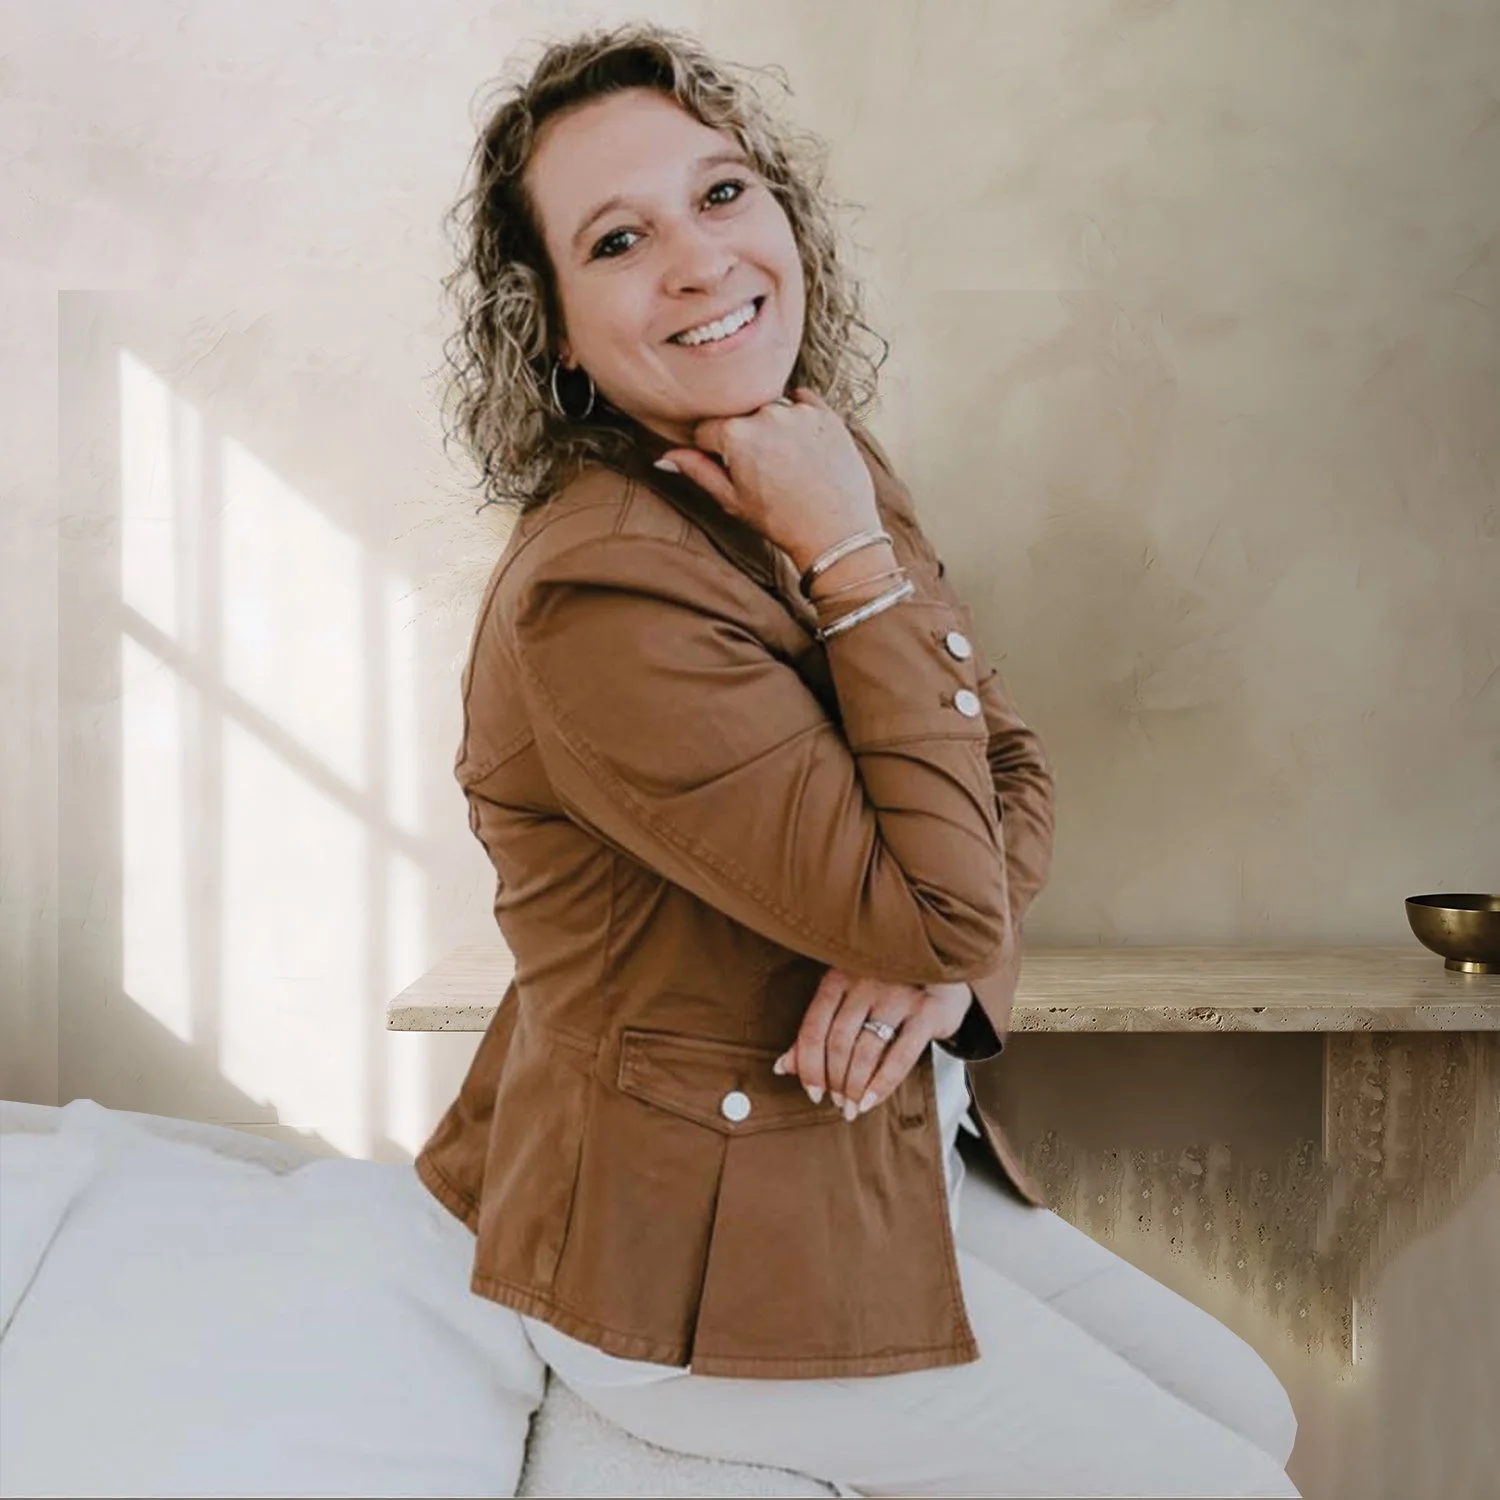
| JENNY TURLEY
REALTOR® | RCS-D™
______________________________
Real Estate Collaboration Specialist – Divorce™
Chattanooga · Hamilton County · Southeast Tennessee